
The Future of Digital Payments in India: Navigating the New UPI Transaction Fees [2025]
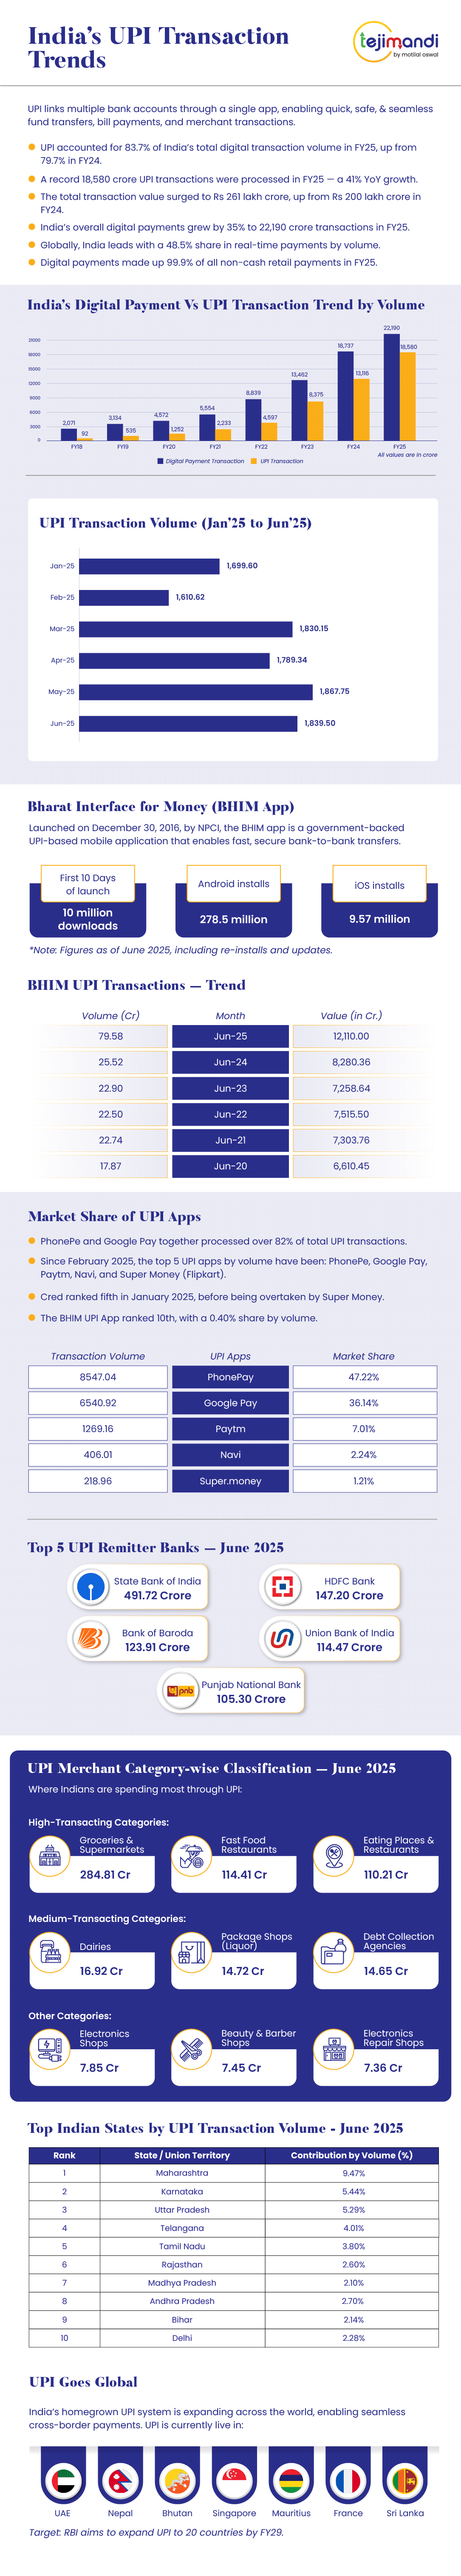
India's digital payment landscape is undergoing a significant shift as the National Payments Corporation of India (NPCI) introduces a merchant fee on larger transactions via the Unified Payments Interface (UPI). This move, aimed at ensuring the financial sustainability of the payment system, is set to change how businesses and consumers interact with digital payments.
TL; DR
- New Fees Introduced: UPI will impose a 0.4% fee on transactions over ₹2,000.
- Consumer Impact: Consumers continue to enjoy free transactions.
- Merchant Impact: Small merchants with monthly collections under ₹100,000 remain unaffected.
- Comparison: Lower fees compared to credit card transactions, which range from 1.5% to 2.5%.
- Sustainability Goal: Aims to make digital payments self-sustaining in India.

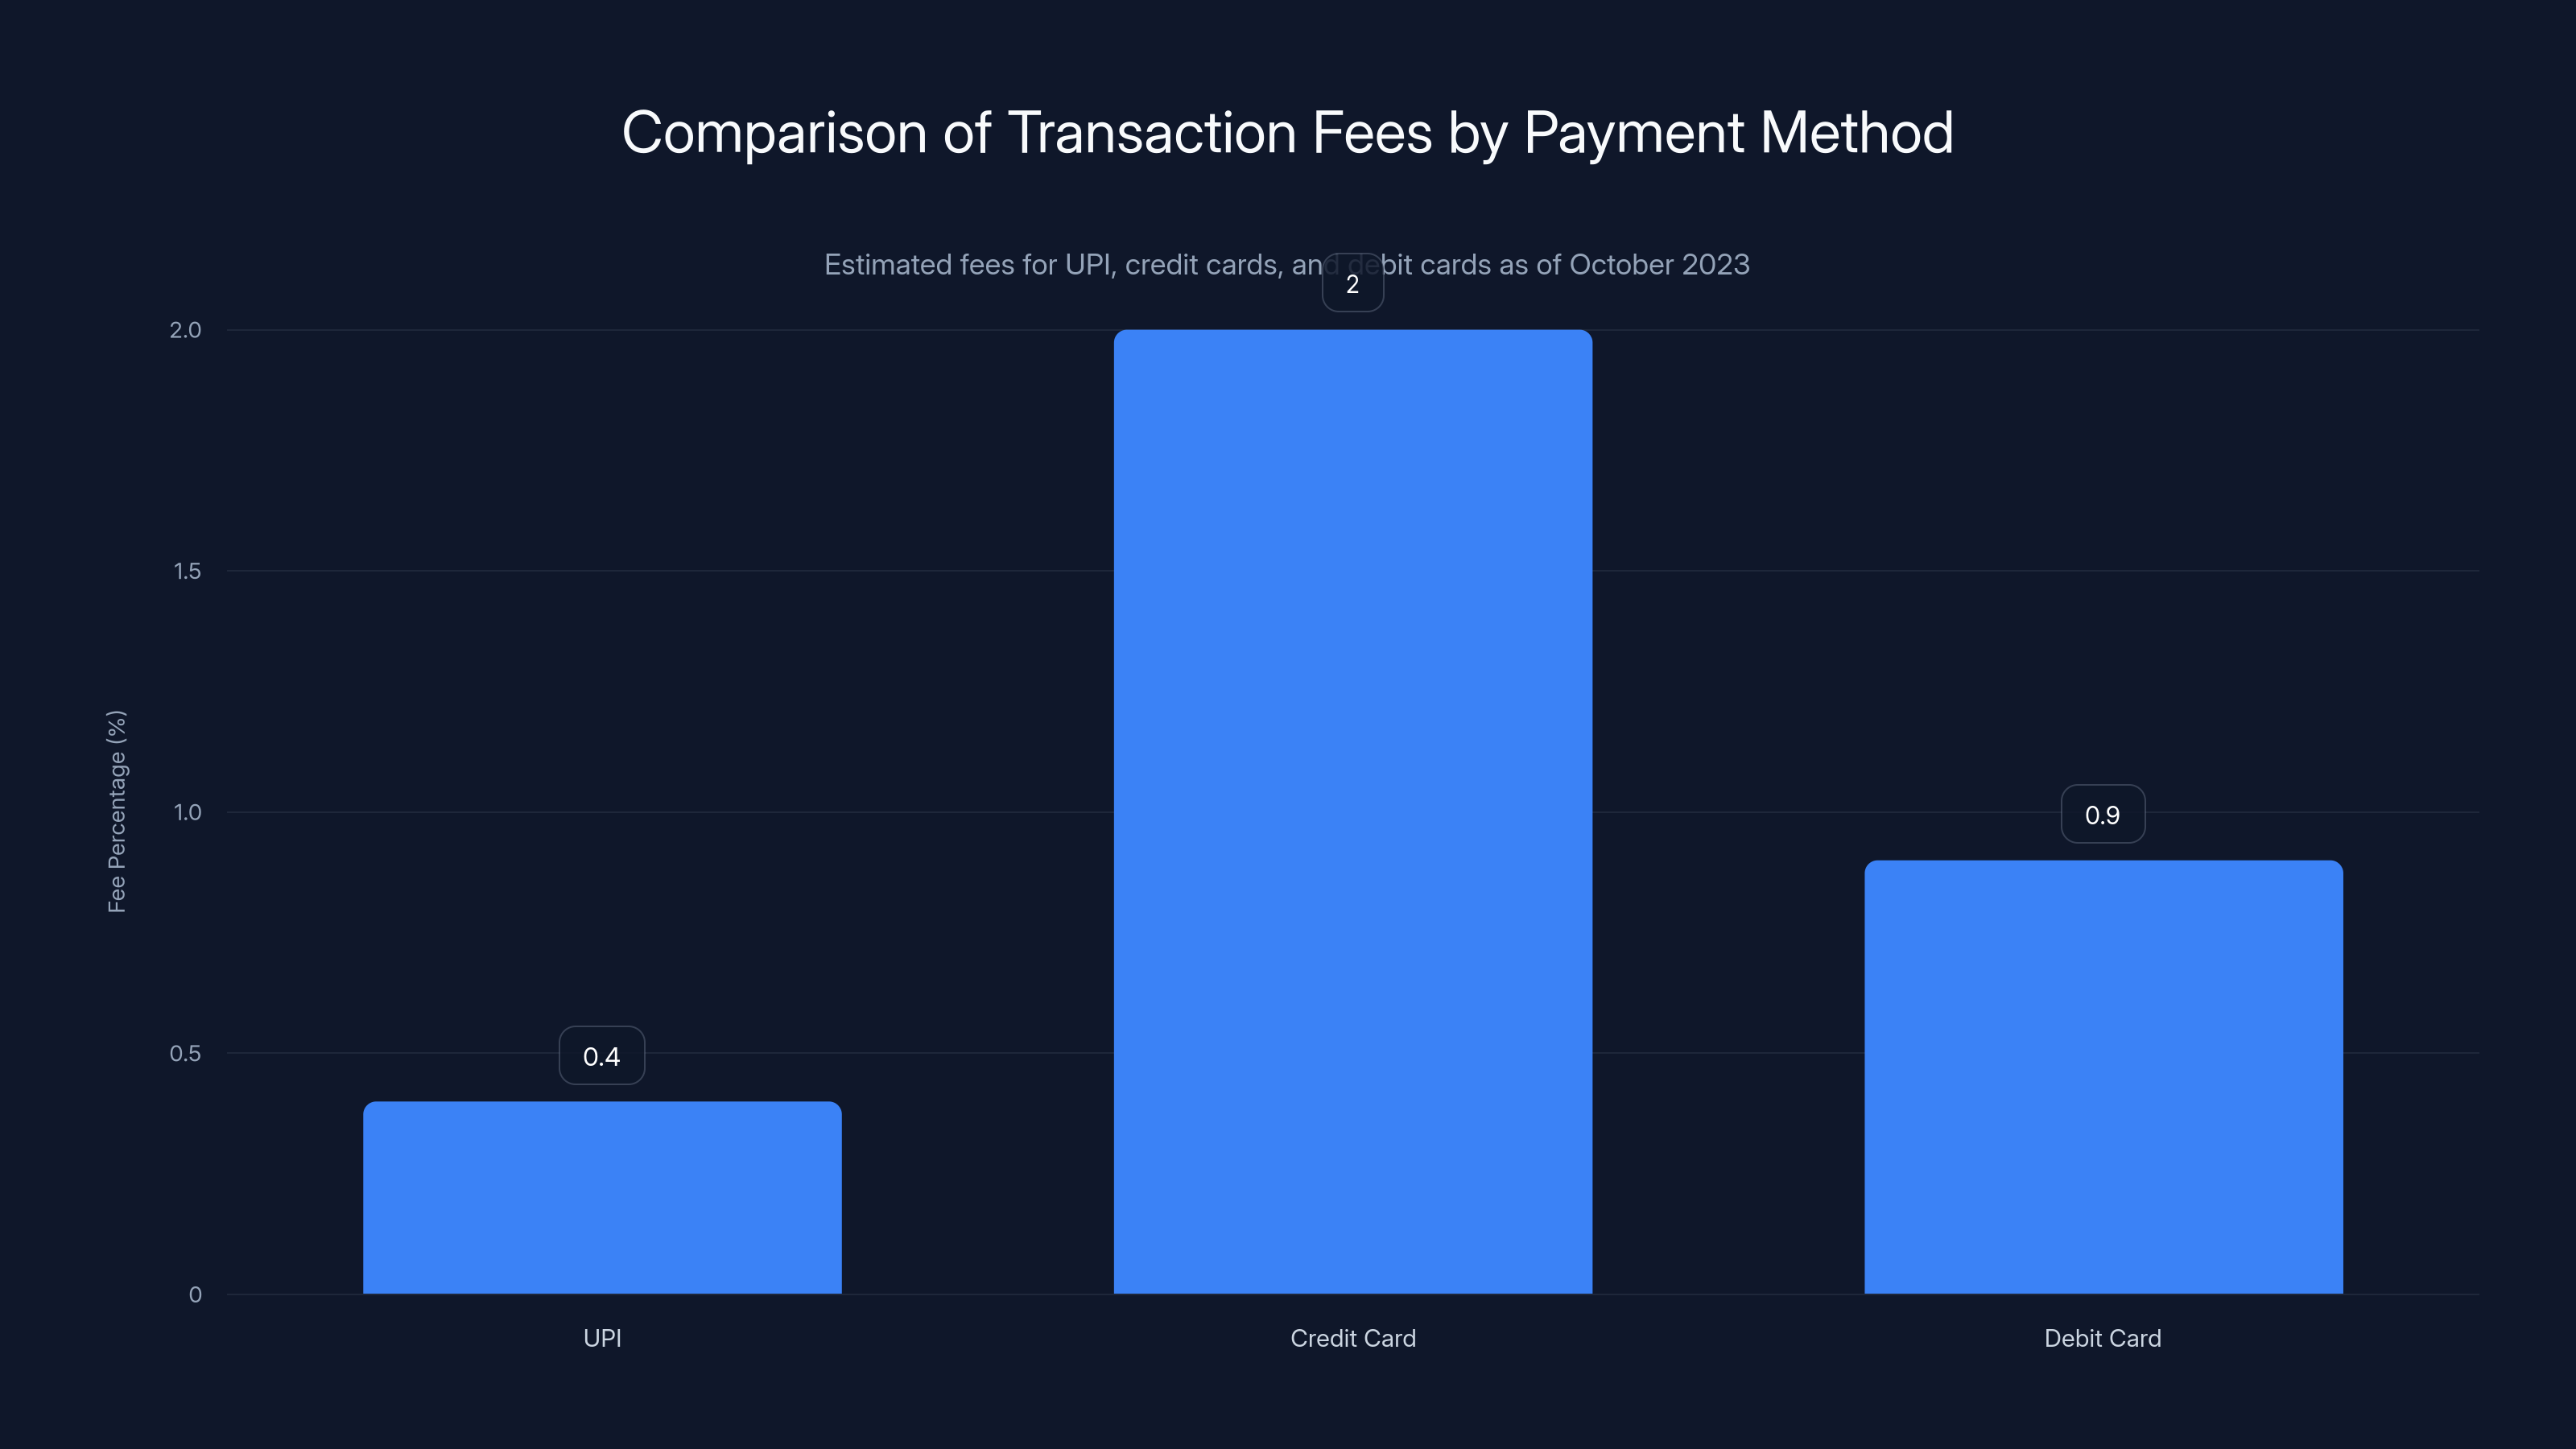
UPI transactions incur a lower fee of 0.4% compared to credit card fees (1.5% to 2.5%) and debit card fees (up to 0.9%). Estimated data.
Introduction
Digital payments in India have seen exponential growth, driven by the convenience and efficiency of platforms like UPI. However, the sustainability of such systems has come into question, prompting the NPCI to implement transaction fees for larger payments. This article delves into the implications of these changes, providing a comprehensive guide to understanding and navigating the new UPI transaction fees.
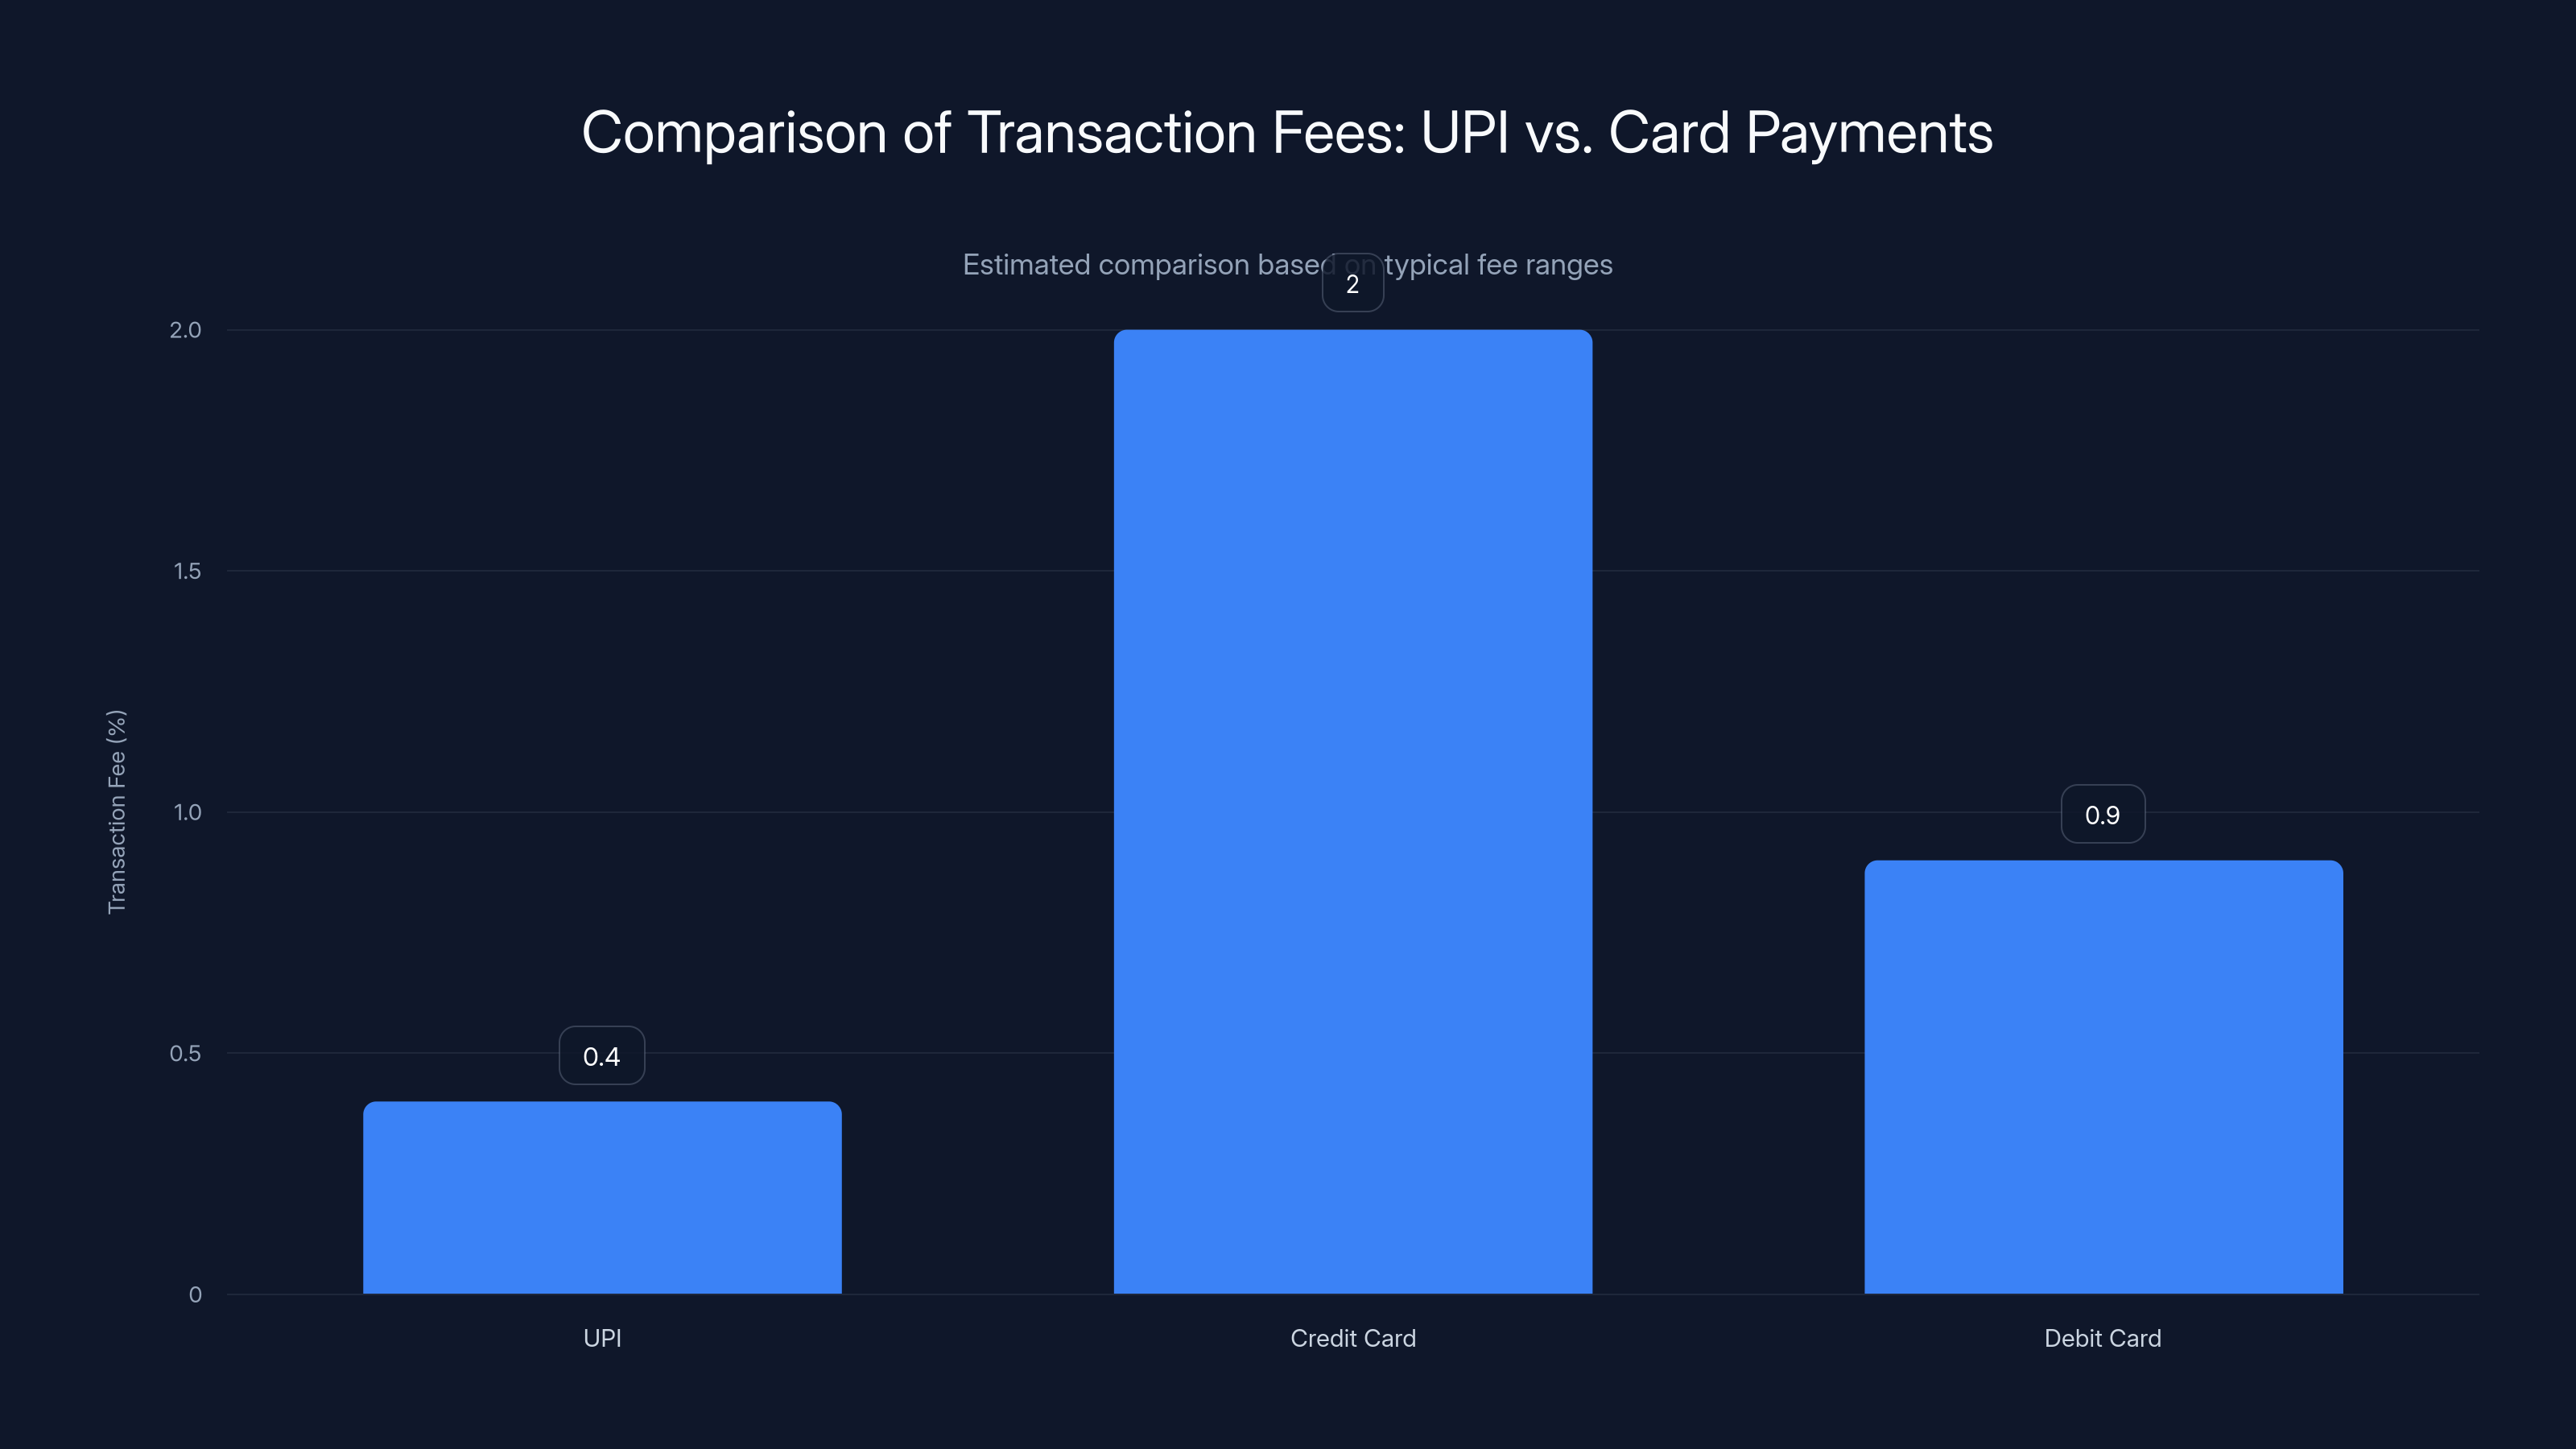
UPI transaction fees are lower compared to credit and debit card fees, making it a cost-effective option for merchants. Estimated data based on typical fee ranges.
Understanding UPI and Its Impact
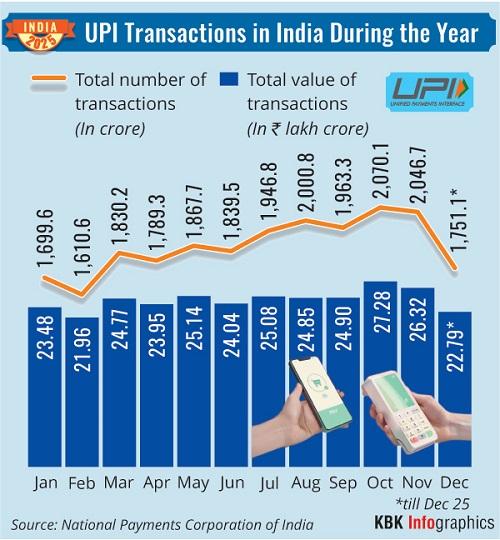
Unified Payments Interface (UPI) has revolutionized the way Indians transact, facilitating billions of transactions monthly. Its seamless integration with banks and ease of use have made digital payments accessible to everyone. But what happens when a system built on free transactions introduces fees?
The Mechanics of UPI
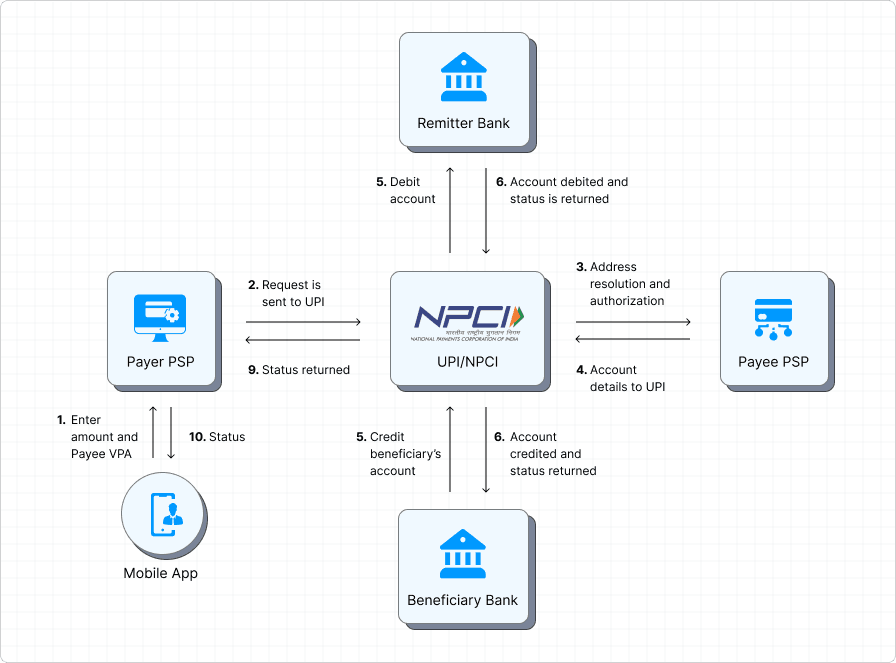
UPI functions as a real-time payment system allowing instant money transfers between bank accounts through a mobile platform. Developed by the NPCI, its interoperability and vast network have been key to its success.
- Real-time processing: UPI processes transactions instantly, with funds reflecting in the recipient's account within seconds.
- Interoperability: Allows users to transact across different banks and payment apps.
- Security: Employs two-factor authentication, enhancing security for users.
Why Introduce Merchant Fees?
The introduction of a 0.4% fee on transactions over ₹2,000 is a strategic move to make UPI financially viable. Unlike credit and debit cards, which have always charged fees, UPI has been free for merchants, leading to questions about its long-term sustainability.
- Financial Sustainability: Ensures that the infrastructure supporting UPI can continue to operate and improve.
- Encourages Smaller Transactions: By keeping smaller transactions free, UPI promotes micro-payments and supports small businesses.
Merchant Fees: A Detailed Breakdown
From October 15, 2023, UPI transactions over ₹2,000 will incur a fee of 0.4%, capped at ₹300 for transactions above ₹75,000. Here's what merchants need to know:
| Transaction Amount | Fee Percentage | Fee Cap |
|---|---|---|
| ₹2,001 - ₹75,000 | 0.4% | ₹300 |
| Above ₹75,000 | 0.4% | ₹300 |
- Small Merchants Exemption: Merchants with monthly UPI collections up to ₹100,000 are exempt from fees.
- Comparison to Card Fees: Credit card fees range from 1.5% to 2.5%, while debit card fees cap at 0.9%.
Key Considerations for Merchants
- Cost Management: Merchants need to evaluate how these fees impact their cost structure.
- Pricing Strategies: Consider whether to absorb the costs or adjust pricing.
- Customer Communication: Clearly communicate any changes in pricing or policies to customers.
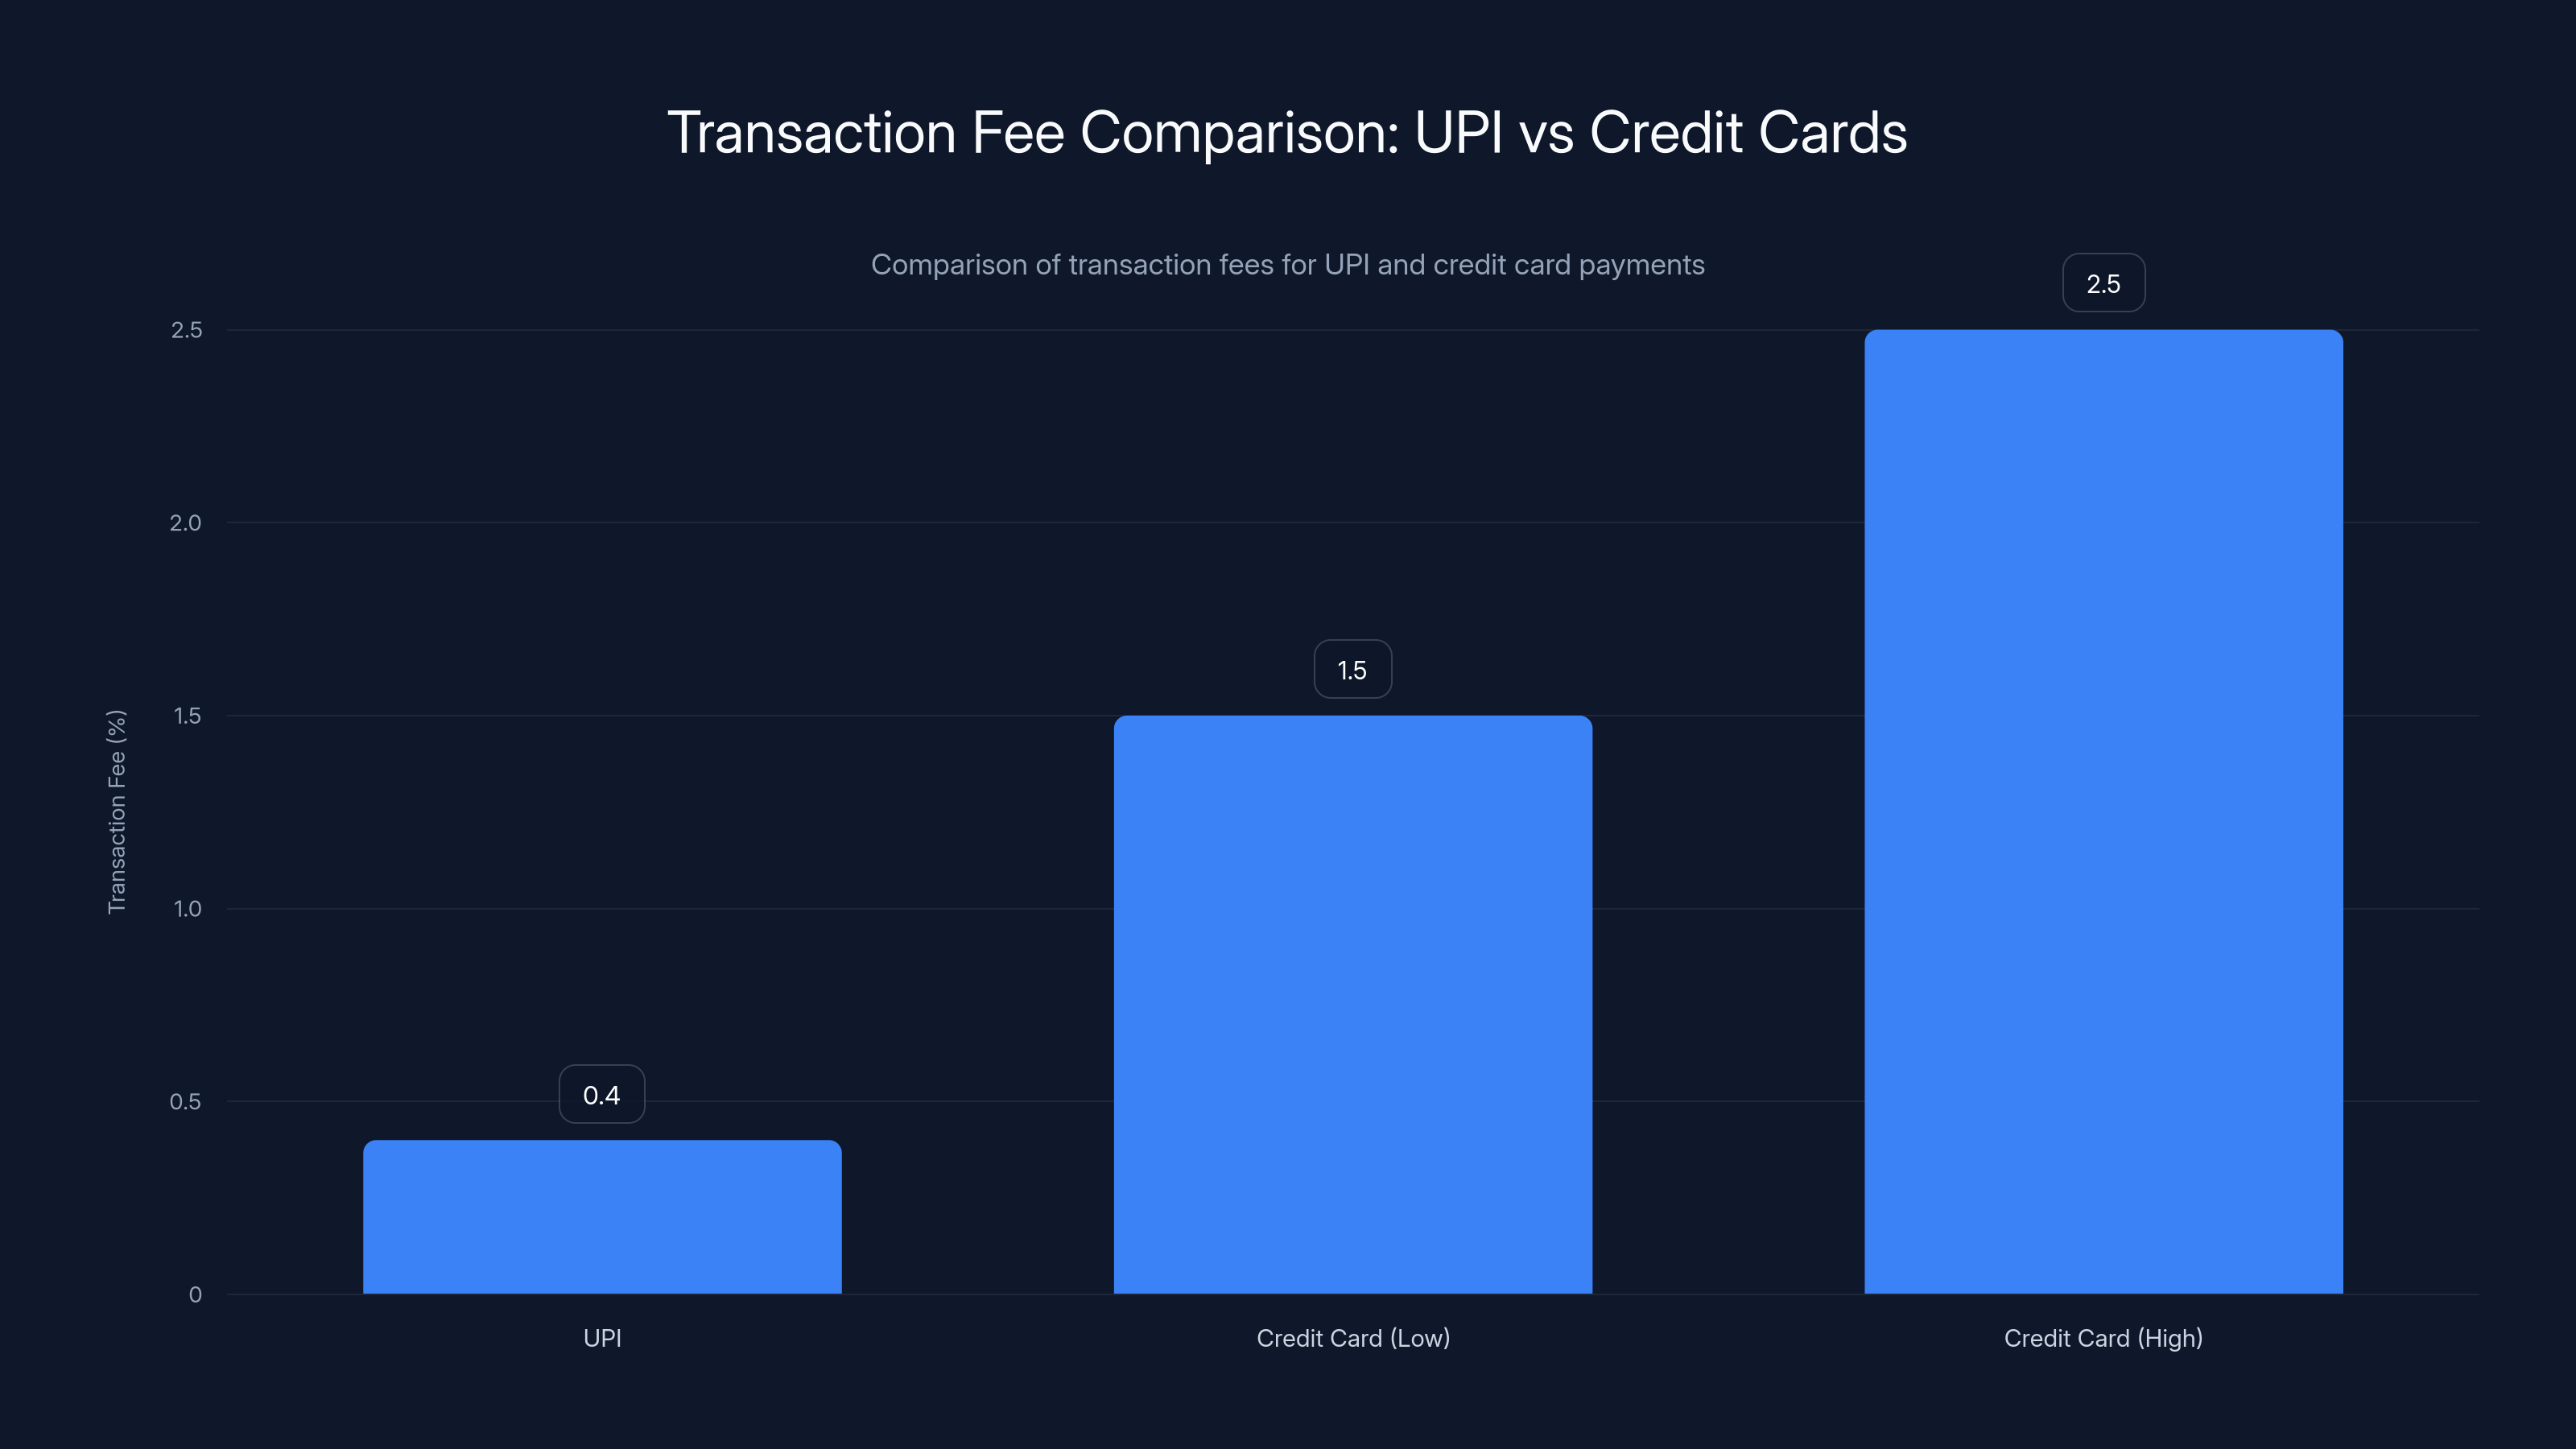
UPI introduces a 0.4% fee on transactions over ₹2,000, significantly lower than credit card fees, which range from 1.5% to 2.5%.
Consumer Perspective: What Remains Unchanged?
For consumers, the introduction of merchant fees may seem like a cause for concern. However, it's important to highlight that these changes will not directly affect consumer transactions.
- Free Transactions: Consumers can continue to use UPI for transactions without incurring fees.
- Enhanced Experience: The sustainability of UPI ensures continued service improvements and innovations.

Best Practices for Merchants
Navigating these changes requires strategic planning and adaptation. Here are some best practices for merchants to consider:
1. Leverage Technology
- Digital Invoicing: Implement digital invoicing to streamline transactions and keep track of payments.
- Analytics: Use transaction data to analyze customer behavior and optimize business strategies.
2. Optimize Payment Processes
- Integrate Multiple Payment Options: Offer a variety of payment methods to cater to different customer preferences.
- Encourage Smaller Transactions: Promote micro-payments to keep transactions under ₹2,000.
3. Enhance Customer Relations
- Transparent Communication: Maintain transparency about any changes in payment policies.
- Loyalty Programs: Implement loyalty programs to incentivize repeat business.
Pitfalls and Solutions
While the introduction of fees may present challenges, there are ways to mitigate potential pitfalls:
Common Challenges
- Increased Costs: Fees may cut into profit margins.
- Customer Resistance: Some customers may be resistant to changes in payment policies.
Solutions
- Cost Absorption: Consider absorbing fees for high-value customers to maintain loyalty.
- Education: Educate customers about the benefits of digital payments and the reasons behind fee introductions.
The Future of Digital Payments in India
With UPI fees now in place, the landscape of digital payments in India is poised for further evolution. Here are some trends to watch:
1. Increased Adoption of Digital Payments
As merchants and consumers adapt to the new fee structure, digital payment adoption is expected to grow. The convenience and efficiency of UPI continue to drive this trend.
2. Innovation in Payment Solutions
The introduction of fees could spur innovation in payment solutions as companies seek to offer competitive alternatives to UPI.
3. Regulatory Developments
Regulatory bodies may introduce new guidelines to ensure fair practices and protect consumer interests in the evolving digital payment landscape.
Practical Implementation Guide
For businesses transitioning into this new phase of digital payments, here’s a step-by-step guide:
Step 1: Assess Current Payment Systems
Evaluate your existing payment systems and identify the impact of UPI fees on your business.
Step 2: Choose the Right Payment Gateway
Select a payment gateway that offers competitive rates and integrates seamlessly with your business operations.
Step 3: Train Staff
Educate your staff on the new payment processes and how to communicate these changes to customers.
Step 4: Monitor and Adjust
Regularly review transaction data to understand the impact of fees and adjust your strategies accordingly.
Conclusion
The introduction of merchant fees on UPI transactions marks a new era in India’s digital payment landscape. While it presents challenges, it also offers opportunities for growth and innovation. By understanding and adapting to these changes, businesses can continue to thrive in the evolving financial ecosystem.
FAQ
What is the new UPI merchant fee policy?
The NPCI has introduced a 0.4% merchant fee on UPI transactions over ₹2,000, capped at ₹300 for transactions above ₹75,000.
How does this affect consumers?
Consumers will not be directly affected as their transactions remain free of charge.
Are small merchants exempt from these fees?
Yes, merchants with monthly UPI collections up to ₹100,000 are exempt from the new fees.
How do these fees compare to credit and debit card fees?
UPI fees are lower, with credit card fees ranging from 1.5% to 2.5% and debit card fees capped at 0.9%.
What strategies can merchants use to manage these fees?
Merchants can optimize payment processes, leverage technology, and enhance customer relations to manage the impact of fees.
Will the introduction of fees spur innovation?
Yes, the introduction of fees is likely to encourage innovation in payment solutions as companies seek competitive alternatives.
What are the future implications for digital payments in India?
The future of digital payments in India will likely see increased adoption, innovation in solutions, and potential regulatory developments.
How can businesses implement new payment strategies effectively?
Businesses can implement new payment strategies by assessing current systems, choosing the right payment gateway, training staff, and monitoring performance.
Key Takeaways
- UPI introduces a 0.4% fee for transactions over ₹2,000 to ensure sustainability.
- Small merchants with collections up to ₹100,000 remain exempt from fees.
- Consumer transactions remain free, preserving user experience.
- Compared to credit cards, UPI fees are significantly lower.
- Fee introduction may drive innovation in payment solutions.
- Merchants should assess and adapt strategies to manage new fees.
- Digital payment adoption in India continues to rise.
- Potential regulatory developments could shape the future landscape.
Related Articles
- Visa, Mastercard, and Coinbase: Unveiling a New Era with Open USD [2025]
- Apple Wallet vs. Google Wallet: Understanding Their Differences [2025]
- 6 Expert Ways to Maximize Your Apple Wallet [2025]
- UBS Mandates AI Skills for All New Employees [2025]
- Decoding Microsoft's Azure Revenue Disclosure: A New Era in Financial Transparency [2025]
- Markiplier: From YouTube Star to GoPro's Biggest Shareholder [2025]


